Inside the 2026 M&A Market: 10 Takeaways From Klehr Harrison’s Third Annual M&A Summit
The Klehr Harrison Harvey Branzburg LLP Corporate and Securities Department recently hosted its third annual M&A Summit, bringing together dealmakers, business owners, executives, and advisors for a morning focused on the current M&A landscape and the issues shaping transactions today. The program featured an opening address by Klehr Harrison Corporate and Securities Department Co-Chair Bill Matthews and two panels addressing both the state of the M&A market and the lifecycle of an M&A transaction.
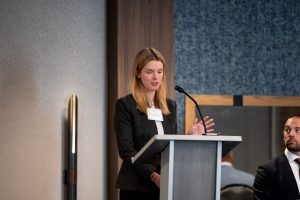
Pictured above: Klehr Harrison Corporate and Securities Partner Elizabeth Webb Bucilla moderating the State of the M&A Market (3rd Quarter 2026) panel at the M&A Summit.
The Summit’s first panel, State of the M&A Market (3rd Quarter 2026), was moderated by Klehr Harrison Corporate and Securities Partner Elizabeth Webb Bucilla, whose practice focuses on middle-market M&A transactions for clients including private equity firms, start-ups and family-owned businesses on both the buy-side and sell-side. She was joined by Steven Higgins, Managing Director of Delancey Street Partners; Parker Kolodka, Senior Vice President of Transactional Risk at Marsh; Nathan Meisberger, Vice President in J.P. Morgan’s Private Business Advisory Group; and Scott Pinchak, Managing Director at Sageworth. Drawing on perspectives from investment banking, private business advisory, family-office advisory and transactional risk insurance, Ms. Bucilla guided the panel through the issues that dealmakers are confronting in real time: the rebound in deal activity, the sectors generating interest, changing transaction timelines, artificial intelligence, due diligence, representations and warranties insurance, seller indemnification exposure, contingent consideration mechanisms, valuations and the outlook for the market ahead. The discussion reflected a market that is active but increasingly discerning. Here are 10 key takeaways:
- M&A activity has strengthened, but quality continues to separate the market.
The panelists described 2026 as a considerably stronger year for transaction activity than 2025. Scott Pinchak, for example, noted that his team was working on 12 transactions at the time of the panel, which he characterized as historically high for Sageworth. At the same time, the rebound has not lifted every business equally. Premium assets continue to command strong multiples, while businesses with weaker fundamentals may face a more challenging market.
That distinction became one of the panel’s recurring themes. Businesses with recurring revenue, strong management teams, attractive growth prospects and limited customer concentration are attracting significant buyer interest. By contrast, project-based businesses or companies with significant customer concentration can face challenges regardless of their industry. As the panel observed, understanding the fundamentals of the particular business may therefore be more important than simply identifying a “hot” sector.
- Several sectors are benefiting from powerful investment tailwinds.
In asking where activity has been concentrated, Ms. Bucilla drew out a broad cross-section of sectors attracting buyer interest. Panelists highlighted consumer services, aerospace and defense, manufacturing, specialty distribution, infrastructure, industrial technology, healthcare and business services. Businesses supporting data-center development and electrical-grid investment were singled out as particularly active, including engineering services, specialized staffing and equipment businesses supporting those markets.
The panel also identified increased private equity interest in professional services, including accounting, consulting and engineering firms, and noted emerging conversations involving law firms. Aerospace, defense technology and businesses benefiting from increased defense spending were also identified as areas with buyer interest.
- Buyers remain willing to transact despite uncertainty, but they are becoming more selective.
One of the more striking observations came when Ms. Bucilla asked what had been most surprising about the market. Mr. Kolodka of Marsh pointed to the resilience of buyer confidence despite an environment containing significant macroeconomic and geopolitical uncertainty. His experience suggested that buyers have not broadly stepped away from transactions, including larger deals.
Instead, buyers appear increasingly selective. Where the strategic rationale for an acquisition is compelling, they remain comfortable moving forward. That dynamic helps explain why strong assets can generate significant competitive interest while less attractive businesses encounter more limited prospects.
- Deals may be moving faster, but diligence is not necessarily getting lighter.
Drawing on Klehr Harrison’s own deal experience, Ms. Bucilla highlighted an important change in transaction execution: buyers are increasingly running financing, diligence and purchase agreement negotiations in parallel rather than sequentially. She observed that this approach can shorten the period between signing a letter of intent and closing while helping maintain deal momentum.
The panelists agreed that high-quality, well-prepared businesses can move through a sale process faster but cautioned against equating speed with less scrutiny. Buyers remain focused on financial performance, quality of earnings, tax exposure and other traditional diligence areas. Buyers also are bringing lenders, diligence providers and operating partners into the process earlier, including before exclusivity in some auction processes, allowing them to develop greater conviction about an asset sooner.
- Preparation before going to market is increasingly important.
If faster transaction timelines reward anything, it is preparation. The panel emphasized the advantage available to sellers that enter the market with strong financial reporting, experienced advisors and advanced sell-side diligence, including quality-of-earnings work. Conversely, a business that waits until diligence begins to confront weaknesses in its data or processes may lose valuable momentum.
As Mr. Pinchak of Sageworth put it during the discussion, advisors have increasingly encouraged owners to “get their ducks in a row” before going to market. The panel’s broader point was clear: preparation can affect not merely efficiency, but a seller’s ability to sustain a competitive process and move from LOI to closing.
- AI is simultaneously changing businesses and how buyers diligence them.
Artificial intelligence emerged as one of the panel’s most forward-looking topics. Ms. Bucilla framed the discussion around the growing use of AI and its implications for businesses, M&A diligence and transactional risk.
The panelists cautioned that buyers increasingly want to distinguish meaningful AI integration from superficial uses of technology. AI may also allow diligence teams to analyze data more quickly and identify anomalies or questions that a seller itself has never examined. That can accelerate diligence for a prepared company, but it can also create new issues for sellers whose information has not been organized and tested before the process begins.
- AI is creating a new category of transactional risk.
AI is not simply an operational or valuation issue. It is increasingly an insurance and risk-allocation issue as well.
Mr. Kolodka of Marsh explained that transactional-risk underwriters are scrutinizing how target companies use AI, including how AI models are trained, the source of the underlying information and restrictions governing its use. The concern is concrete: improper use of third-party intellectual property, confidential information or otherwise restricted data can create potentially material exposure. The concern is not limiting R&W insurance coverage, but deal parties should expect AI-related diligence to be part of the process.
- The R&W insurance market remains highly competitive and buyer-friendly.
Representations and warranties insurance has continued its evolution from a specialized transaction tool into a much more regular feature of the M&A landscape. Ms. Bucilla noted that she typically sees R&W insurance on transactions with enterprise values of $20 million or more and highlighted increasing carrier competition, including newer entrants and carriers offering lower retentions in an effort to gain market share.
Mr. Kolodka of Marsh described a dramatic increase in competition among insurers since 2021 and explained that coverage remains broad and relatively inexpensive. With underwriting terms increasingly competitive, claims handling has also become a more significant point of differentiation among carriers. He predicted that the market could ultimately see some insurer retrenchment and consolidation of capacity.
- Earnouts have not disappeared, but sellers may have more room to negotiate their structure.
Turning to purchase-price mechanics, Ms. Bucilla noted that contingent consideration mechanisms such as earnouts had become common tools for bridging valuation gaps in recent years and asked whether their prevalence was beginning to decline. The panel’s answer was more nuanced.
Nathan Meisberger said he was not necessarily seeing fewer earnouts but was seeing greater flexibility in their terms. Buyers may be more willing to consider metrics such as gross profit or gross margin rather than EBITDA, shorter earnout periods and linear rather than all-or-nothing payout structures. The panel tied negotiating leverage here back to the same theme visible throughout the discussion: stronger assets with limited customer concentration are better positioned to negotiate favorable economic terms.
Seller financing has likewise evolved. The panel traced its increased use in recent years in part to a more restrictive lending environment and discussed how changes in interest rates could again lead to greater use as buyers evaluate alternatives to traditional financing.
- The market is favorable today, but dealmakers are watching the horizon carefully.
Ms. Bucilla closed the discussion with the same forward-looking question she poses each year: If the panel reconvened one year later, what headline would describe the M&A market?
The responses captured the tension running throughout the morning’s discussion. Panelists expressed optimism that transaction activity could remain solid, even as they acknowledged continuing uncertainty surrounding interest rates, inflation, geopolitical events, elections and private equity’s backlog of portfolio companies. Steven Higgins observed that market uncertainty itself is constant, even if its source changes, and that businesses and investors ultimately still need to transact. Nathan Meisberger described the current environment as relatively seller-friendly but saw potential risks if financing continues to be expensive.
The Bottom Line
The overarching message from the State of the M&A Market panel was not simply that deal activity has returned. Rather, today’s market is rewarding quality, preparedness and execution.
Strong businesses continue to attract capital and achieve premium valuations. Buyers remain willing to transact but are applying greater scrutiny to the assets they pursue. Sellers that prepare well in advance can take advantage of faster processes and competitive buyer interest, while emerging diligence issues, particularly around AI and cybersecurity, are adding new considerations to an already sophisticated transaction process.
By moving the conversation from market activity and valuations through diligence, AI, R&W insurance, indemnification, earnouts and financing, Ms. Bucilla gave the panel a practical perspective rather than treating the “state of the market” as a discussion of headline statistics alone. Her questions highlighted the intersection between what Klehr Harrison is seeing in current transactions and what investment bankers, advisors and insurers are experiencing from their respective positions in the market.
That perspective reflects the purpose of Klehr Harrison’s annual M&A Summit: bringing together professionals from across the deal ecosystem to compare what they are experiencing in the market, identify emerging issues and provide business owners and transaction professionals with practical insights they can carry into their next deal.